Currency Conversion Surprise
Currency conversion fees can hide inside ordinary card transactions when a purchase is priced in one currency and your card settles in another. The merchant may show a local amount, yet your bank still performs a conversion during settlement. That conversion can include a markup, a fee, or both, and the final exchange rate may differ from the rate you saw on the day you clicked “pay.”
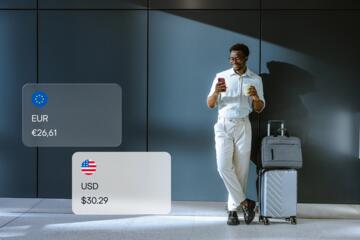
For example, a trip booking site may charge you in EUR while your card settles in USD. The receipt can show an exchange rate or a converted total, but your bank statement often shows a different rate and a separate line item for foreign transaction fees. In some cases, the fee is embedded in the exchange rate rather than listed as a separate charge, which makes the cost harder to notice.
Another common pattern involves “dynamic currency conversion,” where the merchant offers to charge you in your home currency at checkout. That offer can look convenient, yet it often comes with a less favorable rate than the one your card issuer would use. The checkout screen may not clearly separate the conversion markup from the exchange rate, so the total cost becomes difficult to compare.
Where Fees Come From
People often assume the merchant’s displayed price equals the final amount on their statement. That assumption breaks when the transaction passes through multiple steps: authorization, presentment, and settlement. Each step can involve different rates, and the card issuer may apply its own pricing rules for foreign transactions.
Card networks route transactions through authorization systems that confirm funds availability in the transaction currency. Later, the merchant submits the transaction for payment in a process called presentment. Your issuer then converts the amount to your billing currency using its own exchange rate source and fee schedule. If the issuer uses a rate with a markup, the markup can be invisible unless you compare against a reference rate.
Two supporting technologies drive much of the confusion: the card network’s exchange-rate handling and the issuer’s fee policy. The network typically provides a reference rate, while the issuer decides whether to add a foreign transaction fee and whether to show it separately. Some issuers charge a flat percentage; others embed the cost in the rate. I have seen statements where the fee appears as “Foreign Transaction Fee” and others where only the converted total changes, which is frankly annoying when you try to audit spending.
Dynamic currency conversion adds a separate layer. In that flow, the merchant or its payment provider converts the amount before it reaches your issuer. Your issuer may still apply a foreign transaction fee if the final settlement currency differs from your card’s billing currency, but the merchant’s conversion markup can already have increased the cost. The result can be double friction: a worse rate at checkout plus a fee during settlement.
How To Reduce Surprise Costs
Check Your Statement Lines
Start with your most recent statement and look for foreign transaction indicators. Search for terms like “foreign transaction,” “FX,” or the billing currency conversion details. If the statement shows a separate fee line, note the percentage and compare it to the issuer’s published schedule. If the statement shows only a converted total, compare the effective rate to a reference rate for the transaction date.
As a practical aside, I often use a spreadsheet with columns for purchase currency, billing currency, issuer rate, and the fee amount. When the issuer embeds the cost in the rate, the spreadsheet makes the discrepancy obvious. One version detail: the exact wording varies by issuer, and I have seen formats change between statement templates in 2023 and 2024.
Choose The Right Checkout Option
When a merchant offers to charge in your home currency, choose the option that keeps the transaction in the merchant’s local currency. Many payment screens show two choices such as “Pay in [local currency]” versus “Pay in [home currency].” Selecting the local currency typically routes conversion through your issuer rather than through dynamic currency conversion.
At the same time, confirm that your card is set to bill in the currency you expect. Some cards allow you to select a billing currency, and the issuer’s fee policy can differ by billing setup. If you travel with multiple cards, test with a small purchase first, then compare the statement outcome to your expectations.
Compare Issuer Fee Schedules
Read the card’s fee schedule for foreign transactions and note the exact structure. Some issuers charge a percentage of the transaction amount; others charge a flat fee per transaction. A few issuers also waive foreign transaction fees for certain card products, but the waiver can apply only to purchases processed in specific ways.
When you compare cards, use the same scenario: a purchase of a known amount in a foreign currency. Then compare the expected total using the issuer’s fee rule and an exchange-rate reference. If the issuer publishes a method like “rates are based on wholesale rates plus a markup,” you can estimate the range. If the issuer does not publish the method, you can still compare by tracking your effective rate over several transactions.
Use Receipts For Rate Audits
Save the receipt or the online confirmation that shows the transaction currency and any conversion preview. Then compare it to the statement posting date and the final billed amount. The posting date can differ from the purchase date, and the exchange rate can shift between those dates, which explains some mismatches.
For a quick audit, compute the effective exchange rate from the statement: billing amount divided by the purchase amount in the transaction currency. If your issuer charges a separate fee, subtract the fee first to isolate the conversion component. This approach does not require guessing the issuer’s internal rate source, and it works even when the issuer hides the fee inside the exchange rate.
Case Examples
Example 1: Online booking in EUR
A shopper in the US books a hotel priced in EUR using a USD-billing card. The confirmation email shows a converted USD amount and an exchange rate preview. Two days later, the statement posts a different USD total and adds a “Foreign Transaction Fee” line equal to a percentage of the EUR amount. The shopper reduces future surprises by selecting a card with a lower FX fee and by comparing the effective exchange rate on the statement to a reference rate for the posting date.
Example 2: Airport terminal dynamic currency conversion
A traveler buys a small item at an airport kiosk that offers “Pay in USD” at checkout. The kiosk displays a USD price immediately, and the traveler selects that option. The statement later shows a foreign transaction fee even though the checkout used USD, because the underlying settlement currency still triggered the issuer’s FX rules. The traveler switches to “Pay in local currency” on the next purchase and records the effective rate difference, which is often large enough to justify the extra attention at checkout.
Checklist And Comparison
Use this decision support to estimate where the cost comes from and what to check next.
| Situation | Common Hidden Cost | What To Look For | Best Next Step |
|---|---|---|---|
| Merchant charges in foreign currency | Issuer FX markup and/or foreign transaction fee | Statement “Foreign Transaction Fee” or effective exchange rate shift | Compare effective rate and fee to the issuer schedule |
| Dynamic currency conversion at checkout | Merchant conversion markup; possible issuer fee too | Checkout choice “Pay in home currency” plus later FX fee line | Select “Pay in local currency” next time |
| Posting date differs from purchase date | Rate change between authorization and settlement | Statement posting date and final billed amount | Audit using posting date reference rate, not purchase preview |
| Refunds or partial captures | Second conversion on refund; fee handling varies | Separate refund transaction and its FX fee behavior | Track both charge and refund lines separately |
Step-by-step checklist for a single transaction:
- Record the purchase currency from the receipt or confirmation.
- Record the billing currency and billed amount from the statement.
- Find any fee line labeled foreign transaction, FX, or similar.
- Compute the effective exchange rate from the statement amounts.
- Compare to a reference rate for the posting date to separate rate movement from fee markup.
- Repeat once with a second purchase to confirm the pattern, because one-off timing differences happen.
Common Mistakes
People often compare the statement to the exchange rate shown at checkout without accounting for posting-date differences. Authorization previews can use one rate, while settlement uses another, so the mismatch does not always indicate a hidden fee.
Another mistake involves assuming that “no foreign transaction fee” means “no cost.” Some issuers charge no separate fee but still apply a markup in the exchange rate. The only reliable way to detect that is by comparing the effective rate on your statement to a reference rate for the posting date.
Shoppers also miss dynamic currency conversion because the checkout screen can present a single “home currency” total. That presentation hides the conversion markup inside the merchant’s offer. If you want to audit costs, you need to capture which option you selected at checkout and then compare it to the statement behavior.
Finally, people sometimes ignore refunds. A refund can settle on a different date and can trigger a second conversion, and issuers handle FX fees on refunds differently. Tracking the charge and refund separately prevents confusion when the net amount looks “wrong.”
FAQ
Why does my statement show a different rate?
Card issuers convert at settlement using their own exchange-rate method, and the posting date can differ from the purchase date. The statement reflects the final settlement conversion, not the checkout preview.
Is dynamic currency conversion always more expensive?
Dynamic currency conversion often uses a less favorable rate than the issuer’s conversion, and it can add a markup at checkout. The exact cost depends on the provider’s rate and whether your issuer also applies an FX fee.
Where can I find the foreign transaction fee?
Look for a line item on your statement labeled foreign transaction, FX fee, or similar. If the issuer embeds the cost in the exchange rate, the fee may not appear as a separate line.
Do foreign transaction fees apply to refunds?
Refund handling varies by issuer and by how the original transaction was processed. Some refunds reverse the fee, while others treat FX conversion separately, so the statement lines must be checked.
How can I estimate the total cost before paying?
Use the card’s published foreign transaction fee rule and estimate conversion using a reference rate for the expected posting window. Then compare your estimate to the statement after posting to refine your expectations.
Author's Insight
Currency conversion charges come from a chain of settlement steps rather than a single moment at checkout. Issuers decide whether to add a foreign transaction fee and whether to embed costs in the exchange rate, so the same merchant can produce different outcomes across cards. The most reliable consumer method uses your statement: identify the purchase currency, the billed amount, any fee line, and the posting date, then compute an effective exchange rate. This approach works even when the receipt shows a conversion preview that later changes.
Key Takeaways
- Hidden FX costs usually show up as a foreign transaction fee line or as an exchange-rate markup embedded in the billed total.
- Dynamic currency conversion can add a checkout markup and may still trigger issuer FX fees depending on settlement currency.
- Audit using posting-date amounts from your statement, not only checkout previews.
- Compare cards using the same scenario and track effective exchange rates across a couple of transactions to confirm patterns.